Anthracite price of a large coal mine in Shanxi Province, reduced by 30-80 yuan
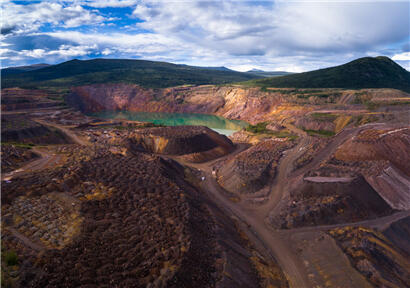
A large mine in Yangcheng, Jincheng City, Shanxi Province is located in Daning Village, Dingdian Town, along the reed river. The mining field is located in the south of Qinshui coalfield, covering an area of 38.83 square kilometers, and the main coal seam is No. 3. The anthracite produced has the characteristics of high calorific value, high mechanical strength, high carbon content, low ash, low sulfur and moderate grindability index. It is a high-quality chemical and power coal, and can be widely used in chemical industry, electric power, metallurgy, building materials and other industries. The annual production capacity is 4 million tons. Coal mine auxiliary construction has a modern coal washing plant with an annual washing capacity of about 4 million tons and a dedicated railway line with an annual transport capacity of about 6 million tons. Coal bed methane is also comprehensively utilized in many forms, such as power generation and heating.
On January 4, 2019, the price of smokeless medium, small and end-coal railways in mines dropped by 20-70 CNY/ton, while the price of highways for all kinds of coal dropped by 40 CNY/ton, and the shipment was under pressure. The mine resumed production on February 11. On Feb. 26, the price of railway and highway decreased by 60 CNY/ton and 40 CNY/ton respectively, while the price of small highway and railway decreased by 60 CNY/ton, resulting in pressure on shipment. On March 12, the shipment of smokeless mid-block was under pressure; the shipment of final coal was smooth; the price of each kind of coal was temporarily stable. On April 1, the price of railway and highway in the middle and small blocks of mine was reduced by 30-60 yuan per ton, and the shipment was under pressure; the price of small roads was reduced by 10 yuan per ton. On June 1, the prices of medium and small pieces of coal mine increased by 20 CNY/ton, while the prices of final coal railway decreased by 10 CNY/ton. In July, prices were temporarily stable and anthracite production was low this month. On August 1, the prices of small anthracite lumps and anthracite end coal were lowered under pressure, and production was normal. And just in the past July, the domestic anthracite market has been weakening steadily, and downstream users are not very enthusiastic about anthracite cargo, which is unfavorable to the anthracite market. Anthracite coal, especially anthracite coal, bears obvious pressure. In July, the price of anthracite in other mainstream coal enterprises such as Henan and Hebei remained stable except that the mainstream coal enterprises in Shanxi Jincheng reduced the price of anthracite end coal by 10-35 CNY/ton. In local mines, coal mines in Gaoping, Qinshui and Yangcheng of Shanxi have lowered the prices of anthracite blocks and final coal, with a single round drop ranging from 10 to 60 CNY/ton. In July, the demand for anthracite purchasing in power, steel and chemical industries is not high, and some coal mines have increased stocks, and the pressure of coal enterprises is more obvious.
In July, the anthracite market in Shanxi continued to develop weakly, the purchase demand of downstream users was not high, and most of the coal mines in the producing areas had certain pressure on the inventory.
From the beginning of the month, the price of anthracite in Shanxi continued to fall. Price reduction began with local mines. Local mines in Qinshui, Zezhou, Yangcheng and Gaoping all lowered the prices of anthracite lump and final coal. The pressure of final coal was more obvious than lump coal, with a single round drop ranging from 10 to 60 CNY/ton. Since then, the mainstream coal enterprises in Jincheng area have lowered the prices of anthracite lump and final coal. The price of anthracite tailings will be reduced by 10-35 yuan per ton under pressure. The demand of downstream users is not high. The coal enterprises will reduce the price under pressure. At present, the main factors leading to the price reduction of coal enterprises are mainly in the demand side, urea and other chemical products tend to be general, and the purchase of raw coal by enterprises is mainly based on the long-term contract without any special growth point; the stock of power plants is always at a high level; the steel mills in Tangshan area are affected by environmental protection and production restrictions, and the demand for fine coal is not high, and anthracite is intact. The volume supply and demand are relatively loose, and some coal mines in Jincheng area indicate that there is a backlog of stocks at the present stage.
Analysis shows that if the downstream demand has not improved significantly in the near future, it is not excluded that the prices of local smokeless blocks and end coal in Shanxi will continue to fall in August, but the single-round decline is expected to be less than 50 CNY/ton.

You May Interested In


High Quality β-Nicotinamide adenine dinucleotide CAS 53-84-9 NADwith ready stock and best price
$3/UNIT FOB


2026-10-16
Trade Alert
Delivering the latest product trends and industry news straight to your inbox.
(We'll never share your email address with a third-party.)

Related News
-
Spain’s Data-Protection Confusion Hits Pesticide Competitiveness
-
Spain’s Data-Protection Confusion Hits Pesticide Competitiveness
-
Qatar LNG Supply Disruption Persists for Nearly Six Months, Exports Plunge 96%
-
Selling the Family Silver for a New Suit? Why Bohai Chemical’s Transformation Drama Got Canceled After Just Two Acts
-
India Raises Cancer Drug Price Caps by 50%
-
Pfizer Warns Germany Over Drug-Pricing Policy
-
New York Targets Additives and GRAS Disclosure
-
Death Toll from Fire at China-Russia Amur Polyolefins Project Rises to 15 as Construction Continues
-
Metso Expands Wear Parts Capacity in China with New Rubber Factory in Quzhou
-
South Korea to Impose Anti-Dumping Duties on Caustic Soda: Chinese Mainland Firms Face Up to 22.21%, Taiwan Region 38.89%
Recommend Reading
-
![From Painting Walls to Total Collapse: The RMB 152 Million Debt That Tore Off the Last Veil of Asia Chuangneng’s Paint Empire]()
From Painting Walls to Total Collapse: The RMB 152 Million Debt That Tore Off the Last Veil of Asia Chuangneng’s Paint Empire
-
![Three Major Indian Chemical Investments Target China's PC Exports]()
Three Major Indian Chemical Investments Target China's PC Exports
-
![Invista Reshuffles Global Nylon 66 Map: Shutting US and UK Plants, Betting Big on China—What Exactly Are They Aiming For?]()
Invista Reshuffles Global Nylon 66 Map: Shutting US and UK Plants, Betting Big on China—What Exactly Are They Aiming For?
-
![Global Biologicals M&A Storm: How 2025 Redrew the Agricultural Innovation Map]()
Global Biologicals M&A Storm: How 2025 Redrew the Agricultural Innovation Map
-
![Australia Launches Anti-Circumvention Trade Probe into China’s 2,4-D Supply Chain]()
Australia Launches Anti-Circumvention Trade Probe into China’s 2,4-D Supply Chain
-
![Business Society’s Market Outlook for Methanol on August 27, 2026: Clearly Downward]()
Business Society’s Market Outlook for Methanol on August 27, 2026: Clearly Downward
-
![Premium Global Chemical Sourcing Requests (22-27 Nov 2025)]()
Premium Global Chemical Sourcing Requests (22-27 Nov 2025)
-
![GM Crop Area Reaches 216 Million Hectares]()
GM Crop Area Reaches 216 Million Hectares
-
![Business Society’s Market Outlook for Fuel Oil 180CST on September 2, 2026: Rising]()
Business Society’s Market Outlook for Fuel Oil 180CST on September 2, 2026: Rising
-
![Business Society’s August 28, 2026 View on Isooctanol Market Trends: Stagnation and Price Rise Warning—Bearish Outlook]()
Business Society’s August 28, 2026 View on Isooctanol Market Trends: Stagnation and Price Rise Warning—Bearish Outlook