Shifting Dynamics in the Global Chemical Industry: The 2024 Top 50 Rankings
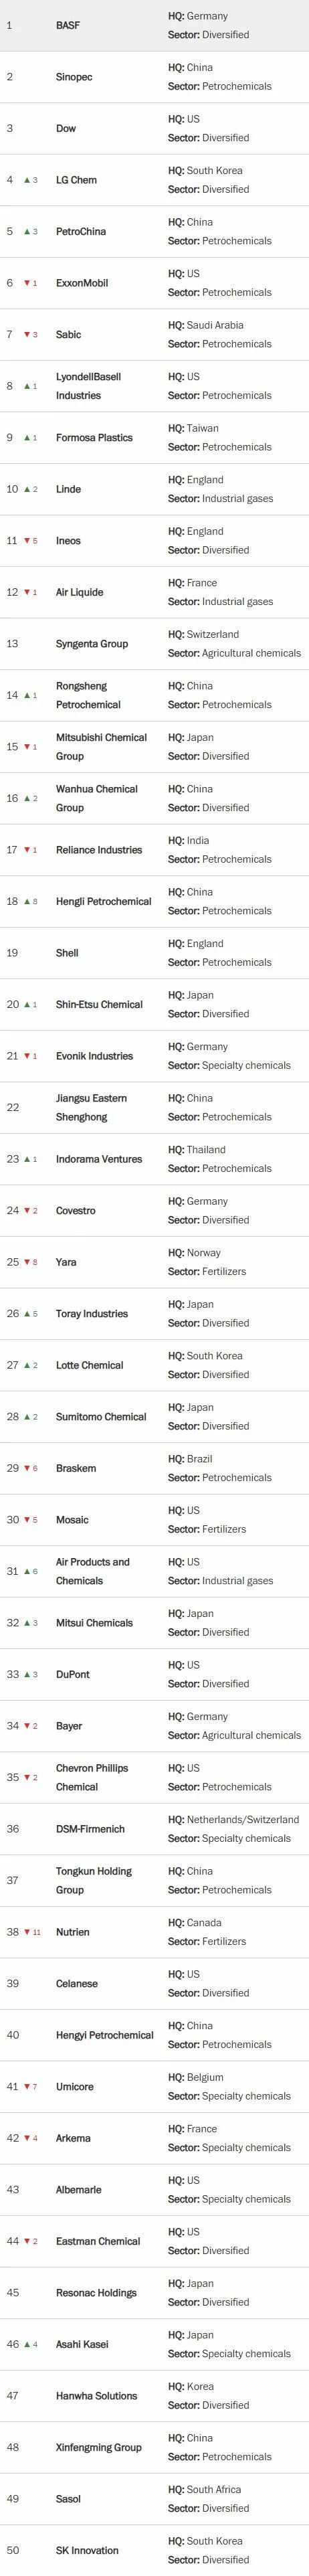
On July 22, 2024, Chemical & Engineering News (C&EN) magazine, which is highly regarded by the industry, announced the authoritative ranking of the "Top 50 Global Chemical Companies in 2024". After fierce competition, the three major companies continue to occupy the top three positions: BASF with its outstanding comprehensive strength once again top, consolidating the global chemical manufacturer's leading position; Sinopec followed closely behind, maintaining the runner-up ranking; Dow Chemical ranked third with solid results. It is particularly remarkable that the number of Chinese enterprises in this list has broken through double digits for the first time, reaching 11, highlighting the booming trend of China's chemical industry.
BASF achieved approximately $74.5 billion in chemical sales in 2023, continuing to consolidate its position as the industry leader. Although there is a gap between Sinopec and BASF, it still holds the runner-up position with $58.1 billion in chemical sales and sound development trend. Dow Chemical ranked third with sales of about $44.6 billion, showing its growth potential to be reckoned with.
In the key period of China's transition from a big petrochemical country to a strong country, petrochemical and chemical enterprises such as Jiangsu Eastern Shenghong and Xinfengming Group came to the forefront and successfully ranked among the top 50 global chemical companies, showing the emerging strength of China's chemical industry. At the same time, PetroChina, Rongsheng Petrochemical, Wanhua Chemical Group and other companies rose in the rankings, further highlighting the vitality and potential of China's chemical industry.
In terms of geographical distribution, this list fully reflects the diversified competitive pattern of the global chemical industry. The US has 10 companies on the list, followed by Japan with seven, while Germany, South Korea and the UK also feature prominently.
The revenue threshold for this year's top 50 chemicals is $8.37 billion, down from last year. Only two companies have sales of more than $50bn, with most in the $10bn to $50bn range. However, it is worth noting that the chemical sales of the Global Chemical 50 companies in 2023 fell by 10.7% year-on-year to $1,036 billion, mainly due to inventory adjustments and severe overcapacity.
In terms of profitability, the situation is not optimistic. Of the 38 chemical companies that disclosed profit data, total profits last year fell 44.1 percent from 2022 to just $54.4 billion. Many companies face falling profits or even losses.
2023 will be a challenging year for European chemical companies. High energy costs and aging assets undermine market competitiveness. At the same time, gas supply disruptions caused by the Russia-Ukraine conflict have further exacerbated the industry weakness. In this context, chemical sales of European companies such as BASF, Ineos and Covestro have fallen sharply. In response, many companies have had to cut costs or shut down inefficient capacity.
Large petrochemical companies are also facing recessionary pressure. Companies such as Dow and ExxonMobil have seen their chemical sales and profits fall, hit by new production capacity in China and the US. Fertilizer companies such as Legg Mason and Nutrien have also been hit hard by falling fertilizer prices.
New entrants to the list this year include Jiangsu Eastern Shenghong and Xinfengming Group, while Hengyi Petrochemical and Tongkun Holding Group successfully returned to the list. At the same time, DSM Firmenich, Abor and other companies also made the list with excellent performance. However, there are also a number of companies that failed to make the 2024 list due to poor performance, which once again confirms the fierce and uncertain competition in the global chemical industry.
It is reported that Chemical & Engineering News magazine annually ranks global chemical companies based on publicly available data, and revises the previous year's ranking based on factors such as exchange rates to ensure the accuracy and fairness of the data.

You May Interested In


High Quality β-Nicotinamide adenine dinucleotide CAS 53-84-9 NADwith ready stock and best price
$3E+1/UNIT FOB


2026-10-25
Trade Alert
Delivering the latest product trends and industry news straight to your inbox.
(We'll never share your email address with a third-party.)

Related News
-
The Last 10% Tariff Trap: A New Chapter in U.S.–China Negotiations on “Fentanyl Tariffs”
-
Vietnam Drives ASEAN Towards a Modern Economy
-
USDA Puts Fresh Money Into Local Food Markets
-
Redwall Raises Prices by as Much as 80%, Songwon Launches Global Increases, and Chemical Companies Are Collectively Passing On Costs
-
U.S. Strikes Three Iranian Tankers as “Tanker-for-Tanker” Escalation Raises Chemical Shipping Risk
-
"No available slots" returns as global shipping rates skyrocket amid multiple factors
-
Panama Canal Delays Deeper Draft Cut, but Transit Capacity Is Still Tightening
-
Middle East Conflict Pushes Up Oil Prices as More Than 100 Chemical Raw Materials Rise in Concentration
-
Crude Tanker Freight From the Americas to Asia Tops $80 Million per Voyage Amid Global Shipping Crunch
-
China, U.S. and Australia Escalate Antidumping Scrutiny: Chemical Exports Face Rising Compliance Pressure
Recommend Reading
-
![Pfizer Warns Germany Over Drug-Pricing Policy]()
Pfizer Warns Germany Over Drug-Pricing Policy
-
![India Raises Cancer Drug Price Caps by 50%]()
India Raises Cancer Drug Price Caps by 50%
-
![From Painting Walls to Total Collapse: The RMB 152 Million Debt That Tore Off the Last Veil of Asia Chuangneng’s Paint Empire]()
From Painting Walls to Total Collapse: The RMB 152 Million Debt That Tore Off the Last Veil of Asia Chuangneng’s Paint Empire
-
![Asia’s Plastics Chain Faces a Shock: Tight Naphtha Supply Drives Up Polymer Costs]()
Asia’s Plastics Chain Faces a Shock: Tight Naphtha Supply Drives Up Polymer Costs
-
![German Chemical Sentiment Hits a Three-Year Low: Supply Disruption Amplifies Pressure on European Manufacturing]()
German Chemical Sentiment Hits a Three-Year Low: Supply Disruption Amplifies Pressure on European Manufacturing
-
![FDA Pushes New Approach to “No Artificial Colors” Claims]()
FDA Pushes New Approach to “No Artificial Colors” Claims
-
![Business Society’s PVC Market Outlook on August 11, 2026: Stable with a Slight Rise]()
Business Society’s PVC Market Outlook on August 11, 2026: Stable with a Slight Rise
-
![Supply Pressure Doubles, Hydrogen Peroxide Prices Continue to Fall in China]()
Supply Pressure Doubles, Hydrogen Peroxide Prices Continue to Fall in China
-
![November MDI Market Gradually Strengthens]()
November MDI Market Gradually Strengthens
-
![Business Society October 22, 2026 Hydrofluoric Acid Trend Analysis: Sideways Fluctuations]()
Business Society October 22, 2026 Hydrofluoric Acid Trend Analysis: Sideways Fluctuations