LG Chem and GS Caltex in Talks to Merge Yeosu Cracker Assets as Korea Pushes Industry Restructuring
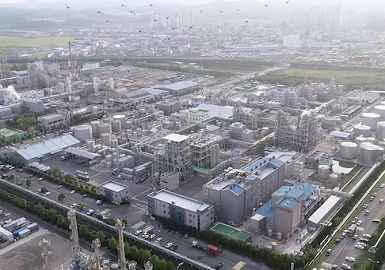
On September 3, LG Chem and GS Caltex announced they are in discussions to integrate their steam cracker operations in Yeosu, South Korea. The move forms part of the government-backed restructuring plan aimed at tackling chronic oversupply in the petrochemical sector.
According to LG Chem insiders, the company is considering selling its Yeosu cracker to GS Caltex, after which both parties would jointly operate the facility through a newly formed joint venture. GS Caltex—a 50:50 refining and petrochemical JV between GS Energy and Chevron—already runs a 0.9 million tonnes per year mixed-feed cracker at the site.
By contrast, LG Chem operates multiple crackers totaling 3.38 million tonnes per year of ethylene capacity, including its No. 2 naphtha cracker in Yeosu, which is a likely candidate for closure under the integration plan. With the ability to process naphtha, off-gas, raffinate, or LPG, the GS Caltex unit is seen as more competitive and flexible compared with LG’s naphtha-based facility.
Analysts note that this merger offers greater synergies than the rival consolidation talks between Lotte Chemical and HD Hyundai around the Daesan complex, given the geographic proximity of LG Chem and GS Caltex’s Yeosu units, which stand virtually side by side.
The talks follow an August 20 agreement between the Korean government and the country’s top petrochemical producers to cut 2.7–3.7 million tonnes per year of ethylene capacity, roughly equal to shutting down three to four crackers. South Korea currently has about 13 million tonnes per year of ethylene capacity, concentrated in Yeosu, Daesan, and Ulsan. The government’s goal is to shrink output by 25% nationwide to restore balance and profitability to the market.
In essence, the LG Chem–GS Caltex deal could set the template for Korea’s petrochemical restructuring drive: large players consolidating overlapping assets, sacrificing older naphtha-based units, and doubling down on more flexible, feedstock-diverse facilities. The outcome will reshape not only Korea’s ethylene footprint but also its role in Asia’s broader petrochemical supply chain.

You May Interested In


2026-09-11
Trade Alert
Delivering the latest product trends and industry news straight to your inbox.
(We'll never share your email address with a third-party.)

Related News
-
Chemical Tanker Explodes Off Oman Coast, Maritime Security Risk Escalates Again
-
South Korea to Impose Anti-Dumping Duties on Caustic Soda: Chinese Mainland Firms Face Up to 22.21%, Taiwan Region 38.89%
-
Death Toll from Fire at China-Russia Amur Polyolefins Project Rises to 15 as Construction Continues
-
Middle East Conflict Hits the Electronics Supply Chain as PPE Resin Shortage Sends PCB Prices Up 40%
-
UAE Withdraws from OPEC
-
The Capital Undercurrent in the Desert: China’s Banks, Saudi Gas, and the “Absent” Chinese Funds
-
Profits Are Rising, but So Are the Risks—China’s Coatings Industry Is Living Through Its Most Awkward Year
-
When Soybeans Lose Weight, Fertilizers Take the Stage: The Industrial Chain Reaction Behind U.S. Farm Subsidies
-
ARLANXEO Launches State-of-the-Art HNBR Plant in Changzhou, Strengthening Asia-Pacific Supply
-
Butadiene Rubber's Cost in China Floor Collapses, Exports Hold the Line
Recommend Reading
-
![Aekyung Chemical Plans to Sell Its Ningbo Subsidiary]()
Aekyung Chemical Plans to Sell Its Ningbo Subsidiary
-
Japanese Plastics Market Accelerates its Shifts to Recycled Materials and Bioplastics
-
![European Petrochemicals Enter 'Era of Downsizing' as Dow, TotalEnergies, Shell Exit Older Cracker Assets]()
European Petrochemicals Enter 'Era of Downsizing' as Dow, TotalEnergies, Shell Exit Older Cracker Assets
-
![Middle East Conflict Hits China Seafood Trade]()
Middle East Conflict Hits China Seafood Trade
-
![Hormuz Closure Raises Cold-Chain Risk]()
Hormuz Closure Raises Cold-Chain Risk
-
![Methanol Market Shows Narrow Fluctuations in China]()
Methanol Market Shows Narrow Fluctuations in China
-
![February 10 Isopropanol Market Remains Stable in China]()
February 10 Isopropanol Market Remains Stable in China
-
![Business Society’s PTA Market Outlook on August 31, 2026: Volatile]()
Business Society’s PTA Market Outlook on August 31, 2026: Volatile
-
![Colombia Makes Preliminary Ruling in Anti-Dumping Investigation into Chinese DOP Imports]()
Colombia Makes Preliminary Ruling in Anti-Dumping Investigation into Chinese DOP Imports
-
![Business Society’s Styrene Market Outlook on August 31, 2026: Weak Rebound]()
Business Society’s Styrene Market Outlook on August 31, 2026: Weak Rebound