Multiple Factors Combine to Drive a Sharp Correction in Ethylene Oxide Prices in May
May 22nd, News
Ethylene Oxide Prices Plunge in May 2026
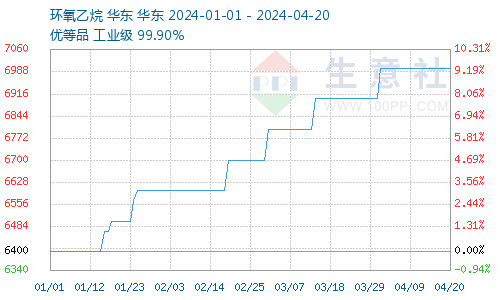
The price of ethylene oxide was lowered in May 2026. According to data, as of May 22, the average market price of ethylene oxide in China was 7,600 CNY per ton, down 15.56% from the average market price at the beginning of the month (May 1), which was 9,000 CNY per ton.
On May 22, 2026, the external price of ethylene oxide in East China was 7,600 CNY per ton; the listed price of ethylene oxide in South China was 7,500-7,600 CNY per ton; the listed price of ethylene oxide in North China was 7,500 CNY per ton; and the listed price of ethylene oxide in Central China was 7,750 CNY per ton.
Analysis of the Reasons for the Significant Price Correction of Ethylene Oxide in May 2026
I. Cost Side: Geopolitical Premium Fades, Ethylene Prices Plunge Sharply
Approximately 70% of the cost of ethylene oxide (EO) stems from ethylene, and ethylene prices are highly correlated with crude oil prices. In the early hours of May 22, a draft agreement between the U.S. and Iran was reached, easing geopolitical risks in the Middle East. As a result, Brent crude oil plunged by more than 6% during the day, driving ethylene prices rapidly downward. The risk premium that had been boosted by geopolitical tensions was quickly squeezed out, completely undermining the cost support for EO. In April, ethylene prices remained at high levels, prompting EO producers to strongly resist price declines. However, as ethylene supplies became abundant and prices continued to ease in May, EO lost its cost floor, forcing prices to adjust downward passively.
II. Supply Side: Maintenance Activities Falling Short of Expectations—Inventory Pressure Gradually Becomes Evident
In May, multiple EO plants in China underwent planned maintenance, but the actual reduction in production was limited, with the industry's operating rate maintained above 53%. The overall supply contraction was less than market expectations. Stimulated by previous high prices, companies' willingness to ship increased. Coupled with the downstream shutdown during the May Day holiday, some goods were stranded, leading to a gradual accumulation of inventory pressure, which forced companies to lower prices to move their stock.
III. Demand Side: Traditional Off-Season + Weak Downstream — Essential Demand Continues to Shrink
May marks the traditional off-season for EO demand. As a result, operating rates in downstream industries such as polycarboxylate superplasticizers and surfactants have declined. Coupled with an underwhelming real estate recovery and dismal end-customer orders, downstream businesses are reluctant to pay high prices for raw materials and are limiting their purchases to only essential needs. Related industries like polyester and textiles are also weakening simultaneously, indirectly dragging down EO demand. Market sentiment remains highly cautious, with buyers showing severe reluctance to make purchases, creating a negative feedback loop of “weak demand → price cuts → further wait-and-see behavior.”
Four, Funds and Sentiment: Taking Profits at High Levels, Decline Reinforces Itself
In March and April, driven by geopolitical tensions, the price of EO surged from 5,500 CNY/ton to 9,000 CNY/ton, accumulating a large number of profit-taking positions. In May, as expectations of easing geopolitical tensions materialized, capital began to exit en masse. Coupled with breaking-through cost levels and pessimistic demand forecasts, market sentiment shifted, prompting traders to panic-sell at lower prices, thereby further amplifying the price decline.

You May Interested In


2026-10-07
Trade Alert
Delivering the latest product trends and industry news straight to your inbox.
(We'll never share your email address with a third-party.)

Related News
-
Business Society September 30, 2026 Maleic Anhydride Trend Analysis: Volatility
-
September Acetic Acid Market Prices Rise Significantly in China
-
Cost Support Drives DMF Market Prices to Rise Amid Volatility in September
-
In September, China's PET hit a high and fluctuated at a high level; in October, the market may show a weak fluctuation at a high level
-
Business Society: China’s Bisphenol A Market Rises in September, May Trade at High Levels in October
-
Business Society September 30, 2026 Fuel Oil 180CST Trend Analysis: Volatility
-
China's Marine Fuel Market Prices Surge in September
-
Polyethylene Prices Rise Then Fall in September, Rebound at the End of the Month in China
-
In September, Most of the Rubber Industry Chain Rose; Only Acrylonitrile Weakened
-
Strong Rally in the September Asphalt Market
Recommend Reading
-
![Business Society’s September 10, 2026 Styrene Market Outlook: Volatile Trend]()
Business Society’s September 10, 2026 Styrene Market Outlook: Volatile Trend
-
![China's Epichlorohydrin Market Supply and Demand Imbalance, Prices Falling]()
China's Epichlorohydrin Market Supply and Demand Imbalance, Prices Falling
-
![Narrow Fluctuations in the Ethanol Market in China in November]()
Narrow Fluctuations in the Ethanol Market in China in November
-
![Business Society’s Hydrofluoric Acid Market Outlook on September 10, 2026: Volatile]()
Business Society’s Hydrofluoric Acid Market Outlook on September 10, 2026: Volatile
-
![Demand Flat, Adipic Acid Prices Decline in May]()
Demand Flat, Adipic Acid Prices Decline in May
-
![Iohexol: Properties, Uses, and Safety]()
Iohexol: Properties, Uses, and Safety
-
![Premium Global Chemical Sourcing Requests (22-27 Nov 2025)]()
Premium Global Chemical Sourcing Requests (22-27 Nov 2025)
-
![Isobutyl: Properties, Uses, and Industrial Applications]()
Isobutyl: Properties, Uses, and Industrial Applications
-
![U.S. Formally Publishes India PFA Trade Cases, Raising New Barriers for Fluoropolymer Supply]()
U.S. Formally Publishes India PFA Trade Cases, Raising New Barriers for Fluoropolymer Supply
-
![China’s New Food-Contact Standards Take Effect, Resetting Compliance for Coatings and Silicone Rubber]()
China’s New Food-Contact Standards Take Effect, Resetting Compliance for Coatings and Silicone Rubber